schedule your free consultation (573) 635-7166
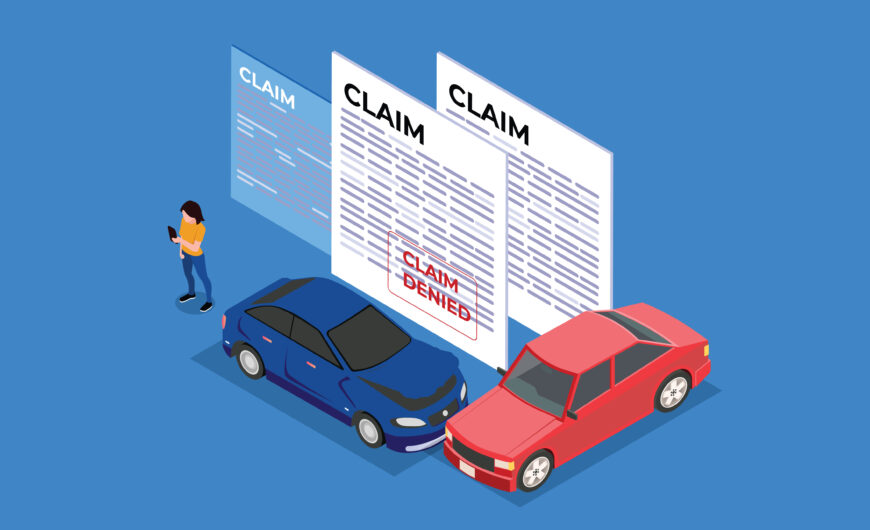
You pay your premiums on time, follow the rules of the road, and trust that your insurance policy will protect you when it matters most. Then an accident happens, and the letter arrives: claim denied. That sinking feeling is something no accident victim should have to face, but the reality is that denied car accident claims are far too common. At Brydon, Swearengen & England P.C., we stand up for accident victims across Jefferson City and the surrounding area. Our team knows how insurance companies operate, and we are dedicated to helping you fight for the compensation you rightfully deserve.
If your car accident claim gets denied, you should:
- Read the denial letter carefully and identify the specific reason for rejection.
- Gather accident reports, medical records, and insurance documents that address the denial.
- Submit a formal appeal and document all communication with the insurer.
- Explore additional options, including filing a complaint or pursuing legal action.
Why Did the Insurance Company Deny Your Claim?
Your first step is to read the denial letter closely. Insurance companies are required to explain their decision in writing, and that explanation is the foundation of your response. Common reasons for denial include:
- Liability disputes: The insurer argues that you were at fault, or that their policyholder was not responsible
- Policy exclusions: Your coverage may have lapsed, or the insurer claims the situation falls outside your policy terms
- Insufficient documentation: Missing photos, repair estimates, or medical records can give the insurer grounds to reject your claim
- Delayed medical treatment: Waiting too long to see a doctor after the accident can allow the insurer to dispute whether your injuries are accident-related
- Pre-existing conditions: The insurer may argue that your injuries existed before the crash
Understanding the stated reason gives you a clear target. A denial based on missing paperwork is very different from one based on a dispute over fault, and your response needs to match the specific issue.
Which Records Can Help You Address the Denial?
Once you know why the claim was denied, gather every piece of evidence that speaks to that reason. Relevant records may include:
- The official police report, including any citations issued at the scene
- Medical records and treatment notes that connect your injuries directly to the accident
- Photographs or video footage of the vehicles, the scene, and your injuries
- Witness statements from passengers, bystanders, or nearby business owners
- Correspondence between you and the insurance company, including prior claim submissions
The more thorough your documentation, the stronger your position when you push back against the denial.
How Do You Ask the Insurance Company To Reconsider the Claim?
Most insurers offer a formal internal appeals process. Submit a written appeal that clearly outlines your argument, cites the relevant sections of your policy, and attaches all supporting evidence. Keep copies of everything you send, and follow up in writing to create a paper trail of how the company responds. Note the date, time, and content of every interaction. If the insurer delays, ignores your appeal, or fails to conduct a proper investigation, that behavior may itself be relevant to any further action you take.
What Options Remain If the Insurer Still Upholds the Denial?
A denial that survives the internal appeal process is not the end of the road. You may still be able to:
- File a complaint with the Missouri Department of Commerce and Insurance: State regulators oversee how insurers handle claims, and a formal complaint can prompt scrutiny of the insurer’s conduct.
- Pursue legal action: Filing a lawsuit often significantly changes the dynamic. Litigation gives you access to tools that are not available during the claims process, and insurers are well aware of the costs and risks involved.
- Explore bad-faith claims: Under Missouri law, insurers that deny valid claims without reasonable cause may incur penalties, attorney fees, and additional damages.
We Help You Stand Up to the Insurance Company
A denied claim does not mean a closed case. At Brydon, Swearengen & England P.C., our team has spent nearly 50 years representing accident victims throughout Jefferson City, and we know exactly how to challenge an insurer’s decision. If your accident claim was denied, contact us today for a free consultation. We are ready to review your case and help you understand your options.
SCHEDULE YOUR FREE CONSULTATION
We Maximize Your Recovery,
With Each & Every Case
We Handle.
*Free consultations only apply to personal injury and workers’ compensation consultations. Charges for consultations apply for other practice areas.
Attorney Advertising. This information is designed for general information only. The information presented should not be construed to be formal legal advice nor the formation of a lawyer/client relationship. Past results and testimonials are not a guarantee, warranty, or prediction of the outcome of your case, and should not be construed as such. Past results cannot guarantee future performance. Any result in a single case is not meant to create an expectation of similar results in future matters because each case involves many different factors, therefore, results will differ on a case-by-case basis. By providing contact information, users acknowledge and give explicit consent to be contacted via the methods of communication provided, including SMS. Message and data rates may apply. Message frequency may vary. Reply STOP to opt out.
NUVEW | Copyright 2026 All Rights Reserved | Accessibility Notice | Privacy statement